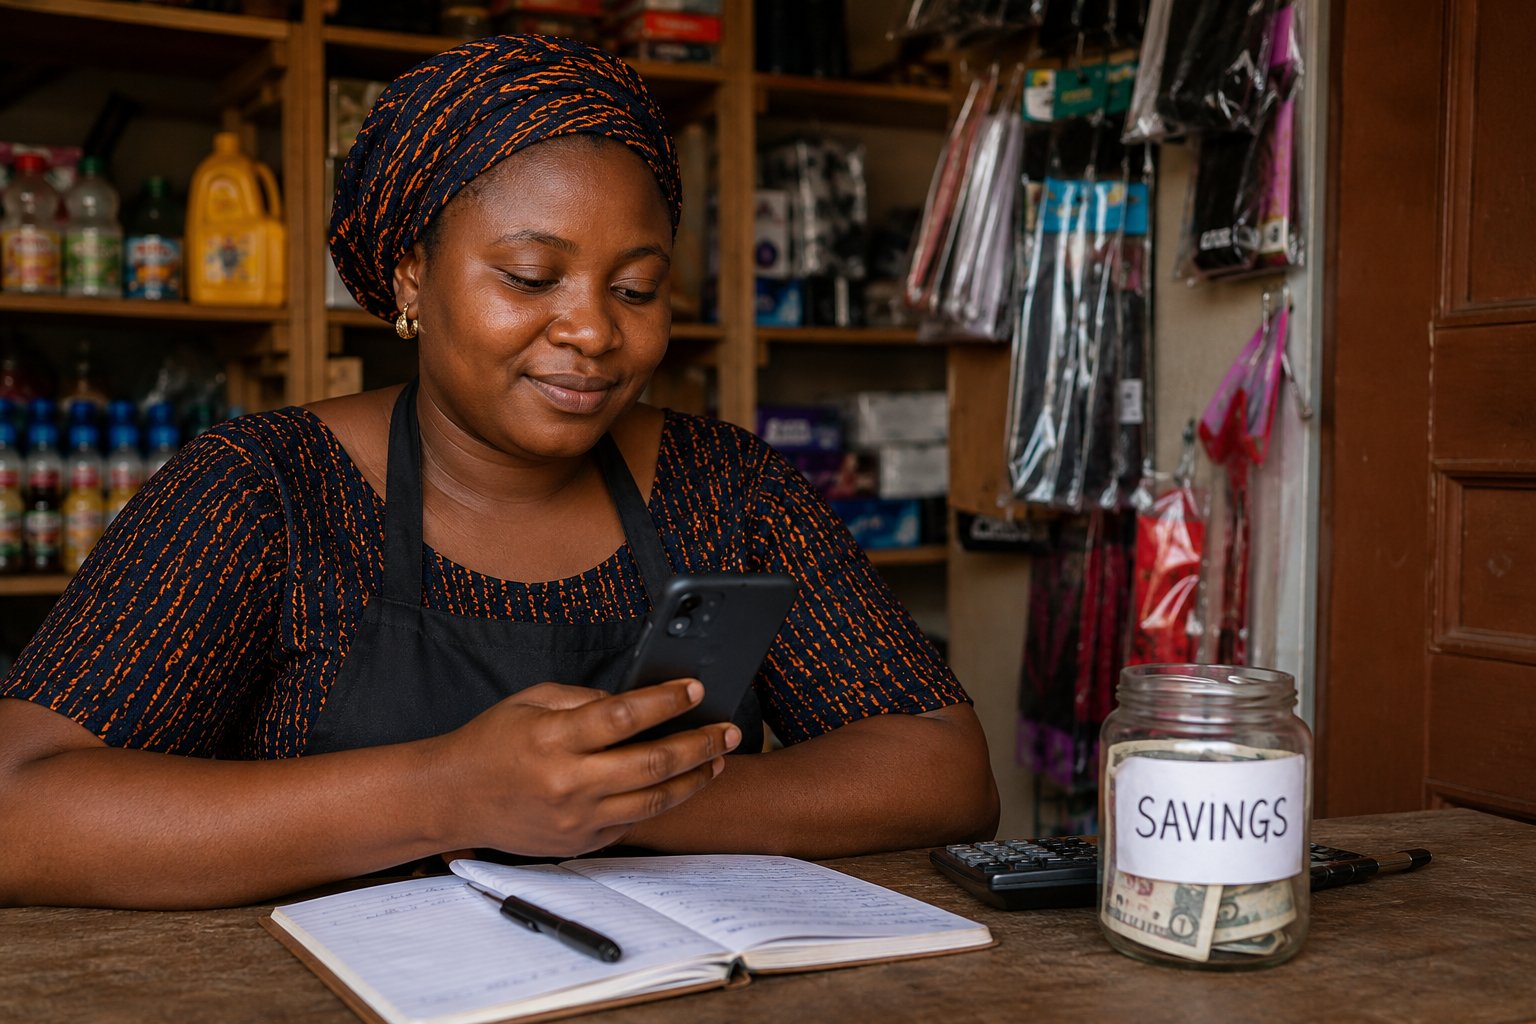

......72.8% of savings disruptions among surveyed customers are linked to unexpected expenses
Moniepoint Microfinance Bank has launched a new range of savings products aimed at helping Nigerians maintain their savings when unexpected expenses arise.
The fintech said its customer survey found that unexpected expenses accounted for 72.8% of reported disruptions to savings plans, while irregular income affected 51% of savers.
However, Moniepoint has not publicly provided details of the survey's sample size, methodology or fieldwork period in the material announcing the campaign.
The launch comes as household finances remain under pressure and many Nigerians try to balance saving with rising everyday expenses.
A 2025 savings report by PiggyVest also found that six in 10 respondents had no emergency savings.
Among those saving less or not saving for emergencies, rising prices was the most commonly cited reason.
Four savings options
Moniepoint's new offering includes Target Savings, Flexible Savings, Fixed Deposit and Save As You Transact.
According to the company's current savings pages, customers can start some of the plans with ₦1,000.
Target Savings pays 11.5% a year and allows customers to access up to 50% of their funds before the target date.
Flexible Savings pays 9.5% annually and allows customers to withdraw without forfeiting accrued interest, according to Moniepoint.
Fixed Deposit offers up to 17.5% annually, with customers able to choose whether interest is paid upfront or at maturity.
Early withdrawal, however, results in the loss of accrued interest.
Save As You Transact automatically moves a chosen amount or percentage into savings when customers make selected transactions such as transfers, airtime purchases or bill payments.
The differences matter because the headline interest rates do not tell the whole story.
Customers must weigh the return against withdrawal restrictions, the period for which money is locked away and the consequences of accessing funds early.
What Moniepoint says
Babatunde Olofin, Managing Director of Moniepoint Microfinance Bank, said the new products were designed around difficulties customers face when trying to save.
"These innovative savings solutions were developed specifically to ease customer pain points. Our ecosystem gives everyone the flexibility to grow their money and access it whenever they need it, combined with some of the best rates in the market — an offering that is truly unique.
"Olofin said the company's objective went beyond encouraging customers to accumulate money."
Our mission is to create financial happiness for everyone. A savings product like this is a critical tool for ensuring people can confidently make their dreams come true while saving for both rainy and sunny days.
The power and discipline to save help propel individuals and businesses toward their goals, while mitigating the harsh effects of unforeseen circumstances.
Backed by the reliable digital payments infrastructure we've built, our customers can find safety, immediate access to liquidity, and the confidence to stay one step ahead of the future while mitigating the harsh effects of unforeseen circumstances.
"These are Moniepoint's stated views about the products. The company has not provided independent evidence showing that the new products will reduce the frequency with which Nigerians abandon or dip into their savings.
Why the launch matters
For many savers, the problem is not simply finding an account that pays interest.An emergency can force someone to choose between protecting a savings target and paying for an immediate need.
A product that allows partial or flexible withdrawals could reduce that conflict, although access to savings can also make it easier to spend money that was intended for a longer-term goal.
This is where the different products serve different purposes.
A customer saving for rent or school fees may prefer a target-based product, while someone building an emergency fund may value easier access.
A business owner with surplus cash may consider a fixed deposit if the money is unlikely to be needed before maturity.
A growing financial services marketMoniepoint says it now serves more than 20 million businesses and individuals.
Its latest impact report said the company disbursed more than $700m in loans to MSMEs in 2025, with three out of four borrowers accessing formal business credit for the first time.
The savings expansion therefore represents a move beyond the company's traditional strength in payments and business banking.
Moniepoint Microfinance Bank received its licence in February 2022 and launched its personal banking product in August 2023, according to the company.
It is regulated by the Central Bank of Nigeria, while its deposits are insured by the Nigeria Deposit Insurance Corporation.
The wider challenge is whether financial products can help Nigerians build meaningful savings while their incomes remain vulnerable to unexpected costs.
Funke Akindele fronts campaign
Moniepoint has also recruited actress and filmmaker Funke Akindele as the face of its "One Step Ahead" campaign.
The campaign uses the Jenifa's Diary universe, which began in 2015, to present the savings message through a setting familiar to Nigerian television audiences.
Akindele's involvement also connects the financial campaign to Nollywood's growing commercial influence.
Her 2025 film Behind the Scenes crossed ₦2bn at the box office, becoming the first Nollywood film reported to have reached that milestone.
Moniepoint's release also describes Akindele as the most decorated individual in AMVCA history, with 10 wins, and says her cumulative career earnings exceed ₦4.7bn.
Those figures were not independently substantiated in the material supplied for the announcement and are not necessary to assess the savings products themselves
What customers should consider
The new products give customers more choice, but flexibility does not remove financial risk.
Customers should check the applicable interest rate, minimum deposit, withdrawal conditions, tenure and consequences of early withdrawal before committing their money.
They should also compare the returns with other regulated savings and investment options rather than assuming that the highest advertised rate automatically represents the best deal.
For Moniepoint, the next test will be whether the products translate the campaign's promise of flexibility into sustained savings behaviour and whether customers clearly understand the conditions attached to each account.
The company's survey provides one reason for the strategy.
More evidence will be needed to establish how widespread the reported savings disruptions are and whether the new products actually help customers withstand them.